The crypto treasury model has largely lost its initial advantage, with most digital asset treasury (DAT) companies no longer charging premiums that allow them to raise capital and accumulate more crypto without diluting existing shareholders, according to a new report by DWF Ventures.
The report released Thursday showed that only four of the 20 largest DATs by assets under management trade above mNAV of 1, meaning their market value exceeds the value of their crypto holdings. They are Bit Digital, Strive, HyperLiquid Strategies and BitMine.
The wide discount suggests that investors are no longer willing to pay the same premium for crypto exposure through publicly traded companies.
Since Michael Saylor’s strategy pioneered the Bitcoin treasury model in 2020, most DAT stocks have underperformed by simply holding the underlying crypto asset, according to DWF. Even among stocks that outperformed DAT, DWF found that the benefit of simply holding cryptocurrencies was generally small.
The report comes as Sequance Communications, a French semiconductor company that launched a bitcoin treasury strategy last year, revealed that it had sold its remaining 314 BTC, completing an exit it began in May by repaying its convertible debt. Sequans currently does not hold any cryptocurrencies on its balance sheet.
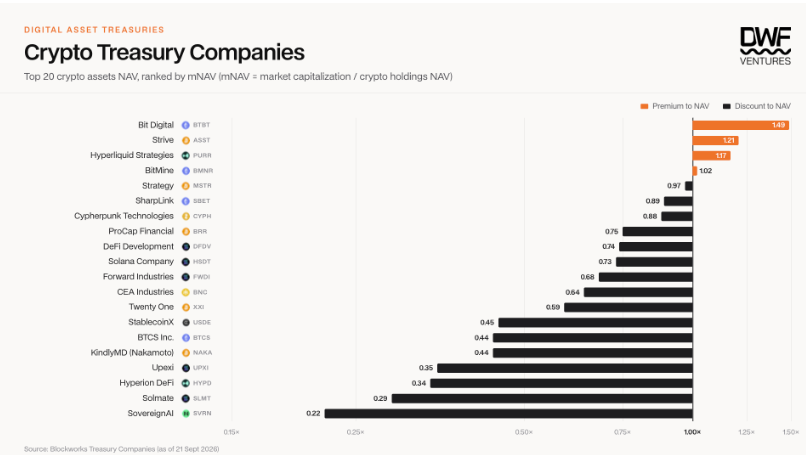
According to DWF, the premium investors paid for DAT stocks typically peaked when the strategy was new and gaining investor attention. For example, the strategy saw its mNAV peak during Bitcoin’s rally in late 2024, when demand for leveraged BTC exposure was strong.
Related: Strategy unlocks $44.1B capital raising capacity to buy more bitcoins
DAT warnings predate the latest recession
DWF is not the only organization to warn of falling mNAV. Standard Chartered raised the issue in September 2025, when bitcoin and the broader crypto market were booming, warning that an “mNAV decline” could lead to massive consolidation among digital asset treasury companies.
Galaxy Digital issued a similar warning last year, arguing that the DAT model “critically relies on a persistent equity premium to NAV.”
This premium allows companies to issue shares and use the proceeds to buy more crypto without diluting existing shareholders’ holdings. If shares are trading below NAV, raising equity to buy more crypto can undermine the strategy’s core financing mechanism.
“If the premium breaks, or worse, flips into a discount, the model starts to break down,” said Galaxy Research analyst Will Owens. wrote.
The model has proven difficult to sustain this year, with bitcoin recovering to around $86,000 before falling from a record high of more than $126,000 last October to below $60,000.
magazine: Bitcoin Treasury Firms May Outperform BTC… But Is It Worth the Risk?