Anyone who has sent a bank transfer overseas is familiar with the painful process of waiting for things like business hours, correspondent banks and settlement times.
In many cases, strapping physical cash to a homing pigeon, or slapping it in an envelope and sending it via DHL will be faster, cheaper and more efficient.
Stablecoins can transfer money across borders around the clock, without waiting for a legacy system to turn on its steam engines.
They can settle transactions 24/7, cut out layers of middlemen and give people access to digital dollars without even needing a traditional bank account.
So do we need banks? And what are the implications of stablecoins offering a faster, cheaper and easier way to move money?
two watches
Anthony Vassallo, director of crypto at Silicon Valley Bank, which failed in March 2023 and now operates as a division of First Citizen Bank, told the magazine that competition from stablecoins will appear across two time frames:
“Two clocks matter. One is slow: currency substitution, deposit erosion, and weakening policy transmission building over months or years. One is fast: a depeg, issuer shock, or banking event that can move capital at software speed within hours.”
European Central Bank Raised Concerns about the effects, arguing that large amounts of stablecoin reserves held in bank deposits could trigger cascading withdrawals if redemption volumes increase.
The bank points to a “liquidity mismatch” between digital money and the banking system that supports it, with reserve assets subject to traditional settlement timelines, while stablecoins last around the clock.
Related: MiCA cracks down on USDT in Europe… but no one else cares
We already saw that dynamic in action in March 2023 when the USD coin lost its dollar peg after Circle revealed that $3.3 billion in reserves were held in failed Silicon Valley banks. The incident turned the banking failure into a stable coin crisis almost overnight, with authorities having to step in to guarantee deposits.
Large stablecoin reserves could trigger a bank run. Source: ECB
Bank runs are quite extreme cases; The slow clock described by Vasallo has more of a drip-drip effect. This can happen without a crisis, and it can be difficult to watch as it unfolds.
Dollarization at a slower pace
In July 2026, the Bank for International Settlements seemed 130 economies in stable coin flow and currency deposits in circulation.
It has been found to tend to increase both during times of currency stress and during banking or sovereign crises, where stable coin flows are less affected by capital controls.
So, when people are trying to get out of a depreciating local currency, stablecoins can provide a dollar-based alternative that is hard for local governments to keep.
A September report from Sphere Labs and SVB describes Markets in Argentina, Nigeria and Turkey where demand for stablecoins is closely linked to demand for dollar exposure.
In Argentina, for example, it says 94% of cryptos bought with pesos were in stablecoins, while in Turkey, about $38 billion worth of liras were swapped for stablecoins in one year.
According to Sphere Labs CEO Arnold Lee, stablecoin adoption is largely a dollar story driven by demand for dollars from people who face barriers to access to the traditional banking system. He told the magazine:
“Most of these economies are going to move towards the dollar (…) What I spend my time on is the way it’s done, because a country that manages the transition and a country that goes through it ends up in a very different place.”
If the clock speed increases
A separate BIS survey released in March found That increase in demand for dollar stablecoins could spill over into traditional currency markets.
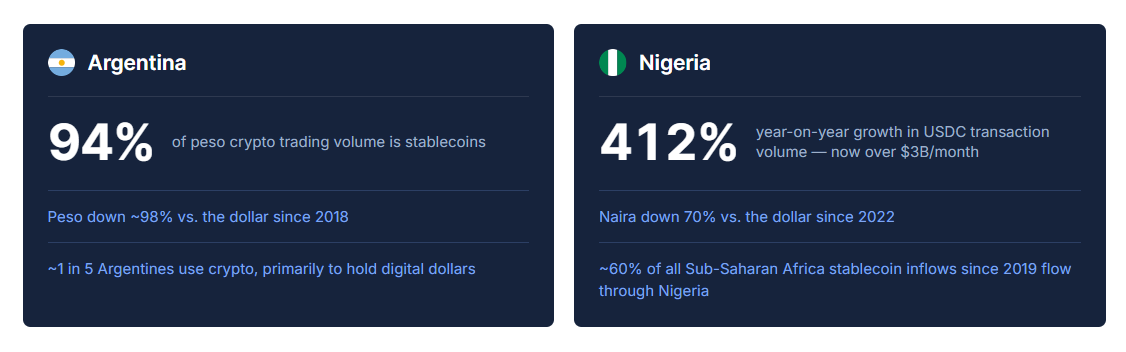
Markets where demand for stablecoins is linked to demand for dollar exposure. the source: Sphere/SVB
The study looked at four major USD-pegged stablecoins across 27 fiat currencies between 2021 and 2025 and found that increased demand for stablecoins could put downward pressure on local currencies and make the dollar more expensive to obtain through FX swaps, when financial intermediaries are already under pressure.
“When citizens of hyperinflation economies move from local currencies to digital dollars, financial circulation weakens, deposit bases erode, and pressures build faster than central banks can respond,” Lee said.
Related: Stablecoins not credible for payments at scale, BIS chief says
The Sphere report describes how, during a dispute between the United States and Colombia in January 2025, Colombians operated funds in digital dollars. Banks and currency exchanges were closed for the weekend, but casa de blockchain is always open.
That is where the ECB’s warning rings loudest.
Under the current Market for Crypto Assets (MiCA) regulations, stablecoin issuers must be kept At least 30% of reserves in bank deposits, and up to 60% for significant asset-referenced tokens (ARTs).
Lessons for the rise of stablecoins. Source: BIS
The European System of Central Banks proposed earlier this month to move away from this fixed percentage, to a requirement based on how quickly reserve assets can be made available.
This avoids a doomsday scenario where heavy redemptions dry up commercial lenders overnight; Tether CEO Paolo Arduino warned in 2024, when he called MICA “very dangerous for stablecoins.”
So the same system can create pressure in both directions: money can leave a bank and move into stablecoins when users want digital dollars, then back through the bank when those stablecoins are redeemed.
Technology does not determine which direction the flow takes, but it can determine how fast it happens.
So what is actually displacement?
However, stablecoins are not yet taking over the world. Often they are just an intermediate currency that moves quickly, but still ends up in the bank as dollars.
Pankaj Bengani, former executive at Block and co-founder of stablecoin payments company MELD, told Cointelegraph that about half of the company’s B2B stablecoin offframp volume is in North America.
He said businesses using it include importers, exporters, technology companies, e-commerce marketplaces, payment companies and fintech.
“Most of our data comes back to fiat as soon as the corporate transaction is settled. They are not taking crypto positions. They are using MELD as the settlement rail instead of SWIFT,” Bengani said.
He says the biggest flow is cross-border commercial payments, particularly where businesses earn or hold dollars but suppliers and employees need the local currency.
Supplier payments account for close to a third of business usage, while invoice settlement accounts for about a quarter.
This paints a different picture from people turning to the digital dollar to protect their savings from inflation or to siphon a lump sum out of the fiat system in times of stress.
And this raises another interesting question: If money is not in crypto, what part of the traditional system is actually being displaced? Bengani says:
“Stablecoins won’t replace SWIFT overnight. The realistic change is a thinner correspondent layer, a simple settlement rail replacing the middleman steps that banks have historically needed each other to cross borders.”
In a world where money moves at the speed of thought, that doesn’t mean banks disappear.
Bengani said reserves still sit in bank deposits and treasuries, businesses still need fiat currency and banks are important for “custody, compliance, liquidity and local settlement”.
But what changes in the plumbing — stablecoins don’t remove banks from the financial system as much as change where the friction sits.
Magazine: Exchanges Become Tax Nightmare Reporting Crypto Profits to IRS
Cointelegraph publishes long-form journalism, analysis and narrative reports with subject-matter expertise developed by Cointelegraph’s in-house editorial team. All articles are edited and reviewed by Cointelegraph editors according to our editorial standards. Some articles contain affiliate links, from which Cointelegraph may earn commissions. These relationships do not influence which products we review or our editorial decisions The content published here does not constitute financial, legal or investment advice. Readers should conduct their own research and consult with appropriate professionals. Cointelegraph maintains complete editorial independence.